Loan Repayment Calculator: home loan repayments, monthly, fortnightly or weekly
The Loan Repayment Calculator works out the repayments on a home loan from the amount, the interest rate and the term: monthly, fortnightly or weekly, principal and interest or interest only, with an offset balance and extra repayments, and what a rise of 0.25, 0.5 or 1 percentage point would cost. For example, a $600,000 loan at 6% over 30 years costs $3,597 a month, and $695,029 in interest over the life of the loan.
Figures as at 22 October 2026; the figures use the interest rate you enter, not a lender's published rate
$3,160
a month on a $500,000 loan at 6.5% over 30 years, principal and interest.
+$336
a month on the same loan if the rate rises by 1 point, to 7.5%.
Presm's Loan Repayment Calculator: the standard formula for a loan repaid in equal amounts, with interest worked out monthly on the rate you enter. Your lender's figures can differ with fees, rate changes and rounding. Not financial advice.
The monthly repayment, principal and interest over 30 years, for six loan sizes at five interest rates. Every figure is worked out by the calculator above.
Show
Monthly repayments by loan size and interest rate, principal and interest over 30 years
Loan
At 5.5%
At 6%
At 6.5%
At 7%
At 7.5%
$300,000
$1,703
$1,799
$1,896
$1,996
$2,098
$400,000
$2,271
$2,398
$2,528
$2,661
$2,797
$500,000
$2,839
$2,998
$3,160
$3,327
$3,496
$600,000
$3,407
$3,597
$3,792
$3,992
$4,195
$750,000
$4,258
$4,497
$4,741
$4,990
$5,244
$1,000,000
$5,678
$5,996
$6,321
$6,653
$6,992
Presm's Loan Repayment Calculator: principal and interest, monthly, over 30 years, no offset and no extra repayments. Rates for illustration, not a lender's offer.
What the last RBA decision did to this example
On 30 September 2026 the Reserve Bank raised the cash rate target by 0.25 points, to 4.60%. Lenders set their own rates and decide how much of a move they pass on. If a lender passed the whole rise on to the example here, a $500,000 loan at 6.5% over 30 years, the monthly repayment would go from $3,160 to $3,243: $83 more a month, about $992 more a year.
Principal and interest, $600,000, 6% a year, 30 years.
Monthly
$3,597
Fortnightly (half the monthly)
$1,799
Weekly (a quarter of the monthly)
$899
Interest over the loan, paid monthly
$695,029
Source: Moneysmart (ASIC): pay off your mortgage faster
The same loan with a $50,000 offset and $200 a month extra
As above, monthly repayments, plus $200 a month extra and $50,000 kept in an offset account.
Interest saved
$264,343
Paid off sooner by
7 years 4 months
Source: Moneysmart (ASIC): offset account; Moneysmart (ASIC): pay off your mortgage faster
Five years interest only, then principal and interest
$600,000 at 6% over 30 years, the first 5 years interest only.
Interest only repayment
$3,000 a month
Then, for 25 years
$3,866 a month
Rise
29%
Source: Moneysmart (ASIC): interest only home loans
How the repayment is worked out
A principal and interest loan is repaid in equal amounts: each month the interest is the balance times one twelfth of the yearly rate, and the rest of the repayment brings the balance down, so early repayments are mostly interest and later ones mostly principal. Interest only pays just the interest, so the balance stays the same until the switch, then the whole loan is repaid over the years left: a $500,000 loan at 6.5% interest only for 5 years costs $2,708 a month, then $3,376 (+25%). An offset balance is taken off the balance before the interest is worked out, and an extra amount each repayment goes straight to the principal.
Show
A $500,000 loan at 6.5% over 30 years, principal and interest, monthly: the balance and what was paid
Year
Balance at the end of the year
Interest paid that year
Principal paid that year
Interest paid so far
Year 1
$494,411
$32,335
$5,589
$32,335
Year 5
$468,055
$30,681
$7,243
$157,675
Year 10
$423,881
$27,908
$10,016
$303,121
Year 15
$362,796
$24,074
$13,850
$431,657
Year 20
$278,326
$18,772
$19,152
$536,808
Year 25
$161,521
$11,441
$26,484
$609,623
Year 30
$0
$1,302
$36,622
$637,722
Presm's Loan Repayment Calculator, month by month: $500,000 at 6.5%, principal and interest over 30 years, monthly.
One number is a start. Presm shows the whole picture.
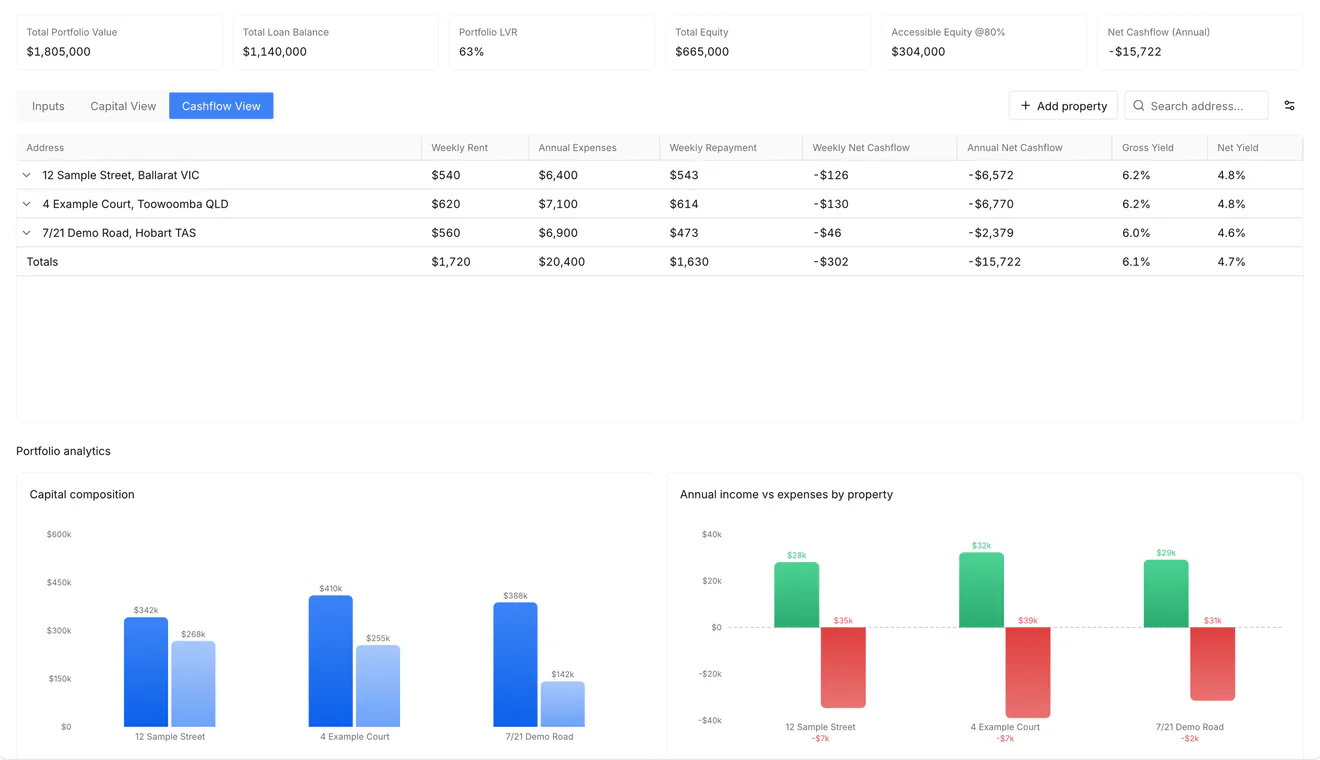
The repayment is one cost of holding a property. Presm puts it beside every other: rent, holding costs and cash flow for each property you own, and what the next one would change.
Portfolio. Value, loans, LVR, equity and cash flow for every property you own, in one table.
Holding costs. What each property costs you weekly, monthly or yearly, every cost on one card.
The Plan. Add the next property and see what changes, 10, 20 or 30 years ahead.
Calculators. Stamp duty, land tax, borrowing power, LMI and more, in one account.
Get startedNo credit card required to get started.
Real Presm screen. Illustrative scenario · fictional data · not financial advice
Questions people ask
Short answers, each checked against the rules and the calculator.
How are home loan repayments worked out?
On a principal and interest loan each repayment pays that month's interest on what you still owe, and the rest pays off the amount borrowed, so equal repayments clear the loan by the end of the term. In the early years most of each repayment goes to interest. A $600,000 loan at 6% over 30 years costs $3,597 a month; over 25 years it costs $3,866, with $559,743 of interest instead of $695,029.
Is it cheaper to pay fortnightly?
Yes, when each fortnightly repayment is half the monthly one. A year has 26 fortnights, so you make the equivalent of 13 monthly repayments instead of 12. On $600,000 at 6% that is $1,799 a fortnight, and the loan is paid off in 24 years 7 months, saving $147,331 of interest. Weekly repayments of a quarter of the monthly amount ($899) work the same way.
How much does an offset account save?
Interest is charged only on your loan balance less your offset balance. Keeping $50,000 in an offset against a $600,000 loan at 6% saves $202,175 of interest and pays the loan off 4 years 8 months sooner, if the balance stays at $50,000 and you keep making the same repayments.
How much do extra repayments save?
Extra repayments go straight off the amount you owe, and early in the loan they cut the most interest. Paying $200 a month more on $600,000 at 6% saves $106,693 of interest and pays the loan off 3 years 11 months sooner.
What happens when an interest only period ends?
During an interest only period your repayments cover only the interest, so the amount borrowed does not fall. When it ends the loan becomes principal and interest over the years left, so repayments rise. On $600,000 at 6% with 5 years interest only, the repayment goes from $3,000 to $3,866 a month, 29% more.
What if interest rates rise?
Under the answer, the calculator shows what a rise of 0.25, 0.5 or 1 percentage point does to your own repayment. On a $600,000 loan over 30 years at 6%, $3,597 a month becomes $3,694 after a rise of 0.25 points, $3,792 after 0.5 and $3,992 after 1. Moneysmart suggests also working out your costs if rates went up by 3 points; you can type any rate into the calculator.