Negative Gearing After the 2026 Budget: A Property Investor's Guide to 2027
The 2026 Federal Budget rewrote negative gearing, the CGT discount and family trust taxation for Australian property investors. Here is what actually changed, what did not, and the four strategies that still build wealth from 1 July 2027 onward.
The 2026 Federal Budget did something Australian property investors have been bracing for since 2019. It actually changed negative gearing. It actually changed the CGT discount. It actually put a floor under family trust distributions.
The papers landed 48 hours ago, the headlines are still hot, and most of what is being written is either doom or denial. Neither is right. The reform is real, the impact is real, and most of the changes do not bite until 1 July 2027. That gap matters.
If you would rather see what this means for your own portfolio in numbers, open Tax Reform Lens and come back. Reading is good. Knowing your number is better.
What Actually Changed
Three policy levers, all switching on 1 July 2027, except discretionary trusts which kick in a year later on 1 July 2028.
Negative gearing limited to new builds
Buy an established investment property after 7:30PM AEST 12 May 2026 and from 1 July 2027 you cannot offset its rental losses against your salary anymore.
The losses still exist on paper but get quarantined inside the property and can only be applied against future rental income or future capital gains from residential property.
Properties acquired before that cutoff are grandfathered until you sell, with full negative gearing forever.
New builds, build to rent, and government housing program investments all keep the old rules permanently.
CGT 50% discount replaced
From 1 July 2027 the 50% CGT discount on assets held more than 12 months is replaced by cost base indexation plus a 30% minimum tax on net capital gains.
Applies to all CGT assets: property, shares, ETFs, crypto, the lot.
Three softeners take the edge off: gains accrued before 1 July 2027 keep the 50% discount via apportionment regardless of when you sell, new build investors can pick whichever method produces a lower bill at sale, and Age Pension recipients are exempt from the minimum tax entirely.
30% minimum tax on discretionary trusts
Note the date: 1 July 2028, not 2027. A full year after the property changes.
From 1 July 2028, trustees pay a 30% minimum tax on the trust's taxable income. Beneficiaries other than corporate beneficiaries get non refundable credits for tax paid by the trustee. Excludes fixed and widely held trusts, super funds, special disability trusts, deceased estates, charitable trusts.
The Government has provided three years of rollover relief from 1 July 2027 to restructure out of a discretionary trust into another entity (company, fixed trust). If you hold property in a discretionary trust, you have until 30 June 2030 to use it.
Which Bucket Are You In?
The reform has ★three dates that matter, and they do different things.
- Budget night, 7:30PM AEST 12 May 2026 decides whether the new negative gearing rules apply to you on a property purchase.
- 1 July 2027 is when the negative gearing and CGT changes start biting.
- 1 July 2028 is when the 30% minimum tax on discretionary trusts kicks in.
Three buyer positions for property right now. Read the one that matches you.
Bucket 1: Acquired before 7:30PM AEST 12 May 2026
Negative gearing: Exempt from the new rules until you sell. Keep claiming losses against salary in 2027, in 2030, in 2040.
CGT: Gains accrued before 1 July 2027 keep the 50% discount via apportionment. If you bought in 2018 and sell in 2030, most of your gain accrued before 2027 and gets the 50% discount, and only the slice that accrued from 1 July 2027 onwards falls under indexation plus the 30% minimum.
Bottom line: Day-to-day cashflow untouched. CGT bill at sale mostly preserved.
Bucket 2: Established property bought between 12 May 2026 and 30 June 2027
You get a transition window before the new rules bite.
Today through 30 June 2027: Negative gearing works normally. Claim against salary on your 2025-26 part-year return and your 2026-27 full-year return.
From 1 July 2027 onward: Losses get quarantined inside the property. Carry forward against future rent or future capital gain on residential property.
CGT: Same universal apportionment as Bucket 1.
Bottom line: A partial year and a full year of normal NG before the new rules bite. Plan around the transition.
Bucket 3: New build bought after 7:30PM AEST 12 May 2026
The cleanest position.
Negative gearing: New builds are permanently exempt. Forever. Even after 1 July 2027.
CGT: New build investors can choose either the 50% CGT discount or the new indexation + 30% minimum method, whichever gives a lower bill at sale.
Bottom line: Government policy is actively pushing capital here.
What If Your Old Home Is The Investment?
Most Australian investors do not buy fresh, they upgrade the family home and keep the old one as a rental, and after this Budget that move has new tax consequences almost nobody is talking about.
The day you move out and start renting the place, two things lock in: every year you lived there stays CGT free forever under the main residence exemption, and your cost base resets to the market value on the day you moved out.
That conversion date valuation now matters more than ever because after 1 July 2027 the rental portion of any future gain runs through the new method instead of the 50% discount, so the higher and more defensible your conversion date valuation, the lower your future tax bill.
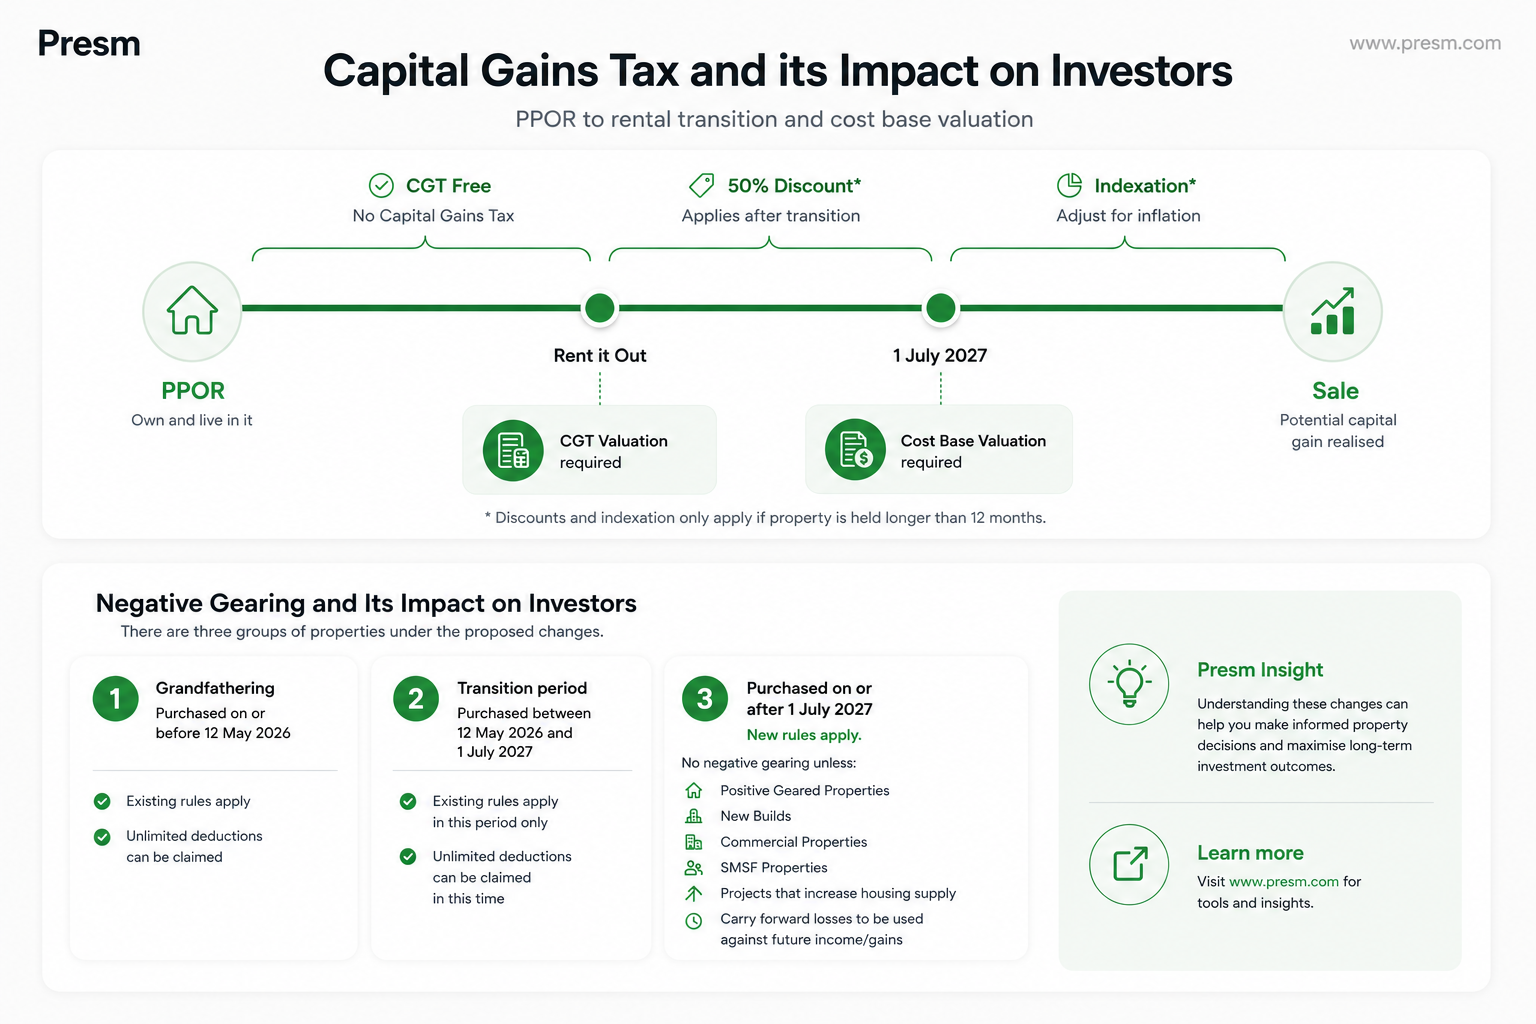
Two valuations now matter
1. The conversion date: The day you moved out is the day your cost base locks in, so get a written appraisal on that day because the ATO accepts a contemporaneous appraisal far more readily than one reconstructed years later from old sale data.
2. 1 July 2027: For any property you still hold on that date, the new CGT method only applies to gains arising from 1 July 2027 onwards while gains accrued before that date keep the 50% discount, so you need a defensible value at 1 July 2027 to split them.
A former family home rented for several years and sold in 2032 runs through three CGT regimes on a single sale:
- CGT free: the years you lived there
- 50% discount: the rental period up to 30 June 2027
- New method: 1 July 2027 through to sale
Clean valuation evidence at both transition points = materially less tax than reconstructing the numbers later.
The 6-year rule still works
The main residence absence rule is untouched, so if you move out and rent the place you can keep treating it as your main residence for up to six years as long as you do not nominate a different property in that window, and inside that window the property stays fully CGT free on sale with no discount, no indexation, no 30% floor, and zero CGT at exit.
Negative gearing on a former PPOR
If you converted before 7:30PM AEST 12 May 2026 you are grandfathered with full negative gearing for the life of the asset, otherwise it counts as a post Budget acquisition giving you the 13.5 month transition window of normal NG before losses get quarantined from 1 July 2027, which makes any conversion date you have already locked in a material tax event worth running through Tax Reform Lens before deciding to sell, hold, or move back in.
[](https://www.risingreturns.com.au)
‼Explained::The one Budget mechanic most commentary is missing
[!takeout]
When your negative gearing gets quarantined from 1 July 2027, the rental losses you can no longer claim against your salary do not vanish. They accumulate against the property year by year, and at sale they come off your capital gain before the new CGT method ever touches it. Get that one detail right and the new rules look very different to the panic version doing the rounds online.
[!example]
The scenario below is the same one we run inside the public CGT model that sits behind Tax Reform Lens, with every assumption disclosed up front so you can argue with any of the numbers.
The setup:
- [house] A regular Australian investor buys a $710,000 established house today, cost base $759,700 once the 7% buying costs are loaded.
- [bank] Borrows $568,000 at 6.5% interest only.
- [calendar] Holds for ten years, sells in 2036 for $1,420,000 less 3% selling costs of $42,600.
- [user] Owner earns $100,000 today, growing at 3% a year to $134,392 by sale year. CPI also assumed at 3%.
- [building] Property starts at $620 a week rent and $200 a week expenses, both growing at 3% a year. Land tax estimated on the Victorian schedule for a $700,000 property (60% of value counts as site value).
- [trending-down] Across the ten years the property runs at a cash loss — interest, expenses and land tax outpace rent. By sale you have accumulated $147,486 of carried-forward losses the new rules would not let you deduct from your salary along the way.
The gross capital gain after costs is $617,700. Three ways the tax bill on that gain can land:
| Pre Budget | Wrong reading | Actual rules | |
|---|---|---|---|
| Less indexation at 3% | : | : | -$231,536 |
| Less 50% CGT discount | -$308,850 | : | : |
| Less accumulated losses | : | : | -$147,486 |
| Taxable gain | $308,850 | $617,700 | $238,678 |
| Tax payable from gain | $134,491 | $273,474 | $102,914 |
| Effective tax rate | 21.8% | 44.3% | 16.7% |
Why the panic number is wrong: it ignores indexation AND your accumulated losses, but add both back (which is what the law actually does) and the $617,700 gain shrinks to $238,678 taxable, your bill drops to $102,914, and you finish $31,577 ahead of the old rules. The whole game is the loss carry forward.
What Did Not Change
Leverage is the whole game and the Budget did not touch it: a bank still lends 80% LVR against a million dollar Brisbane house but not against a million dollar share portfolio. The main residence exemption, depreciation on new builds, interest deductibility, SMSF property strategies, and the 12 month CGT threshold all survive too.
How to Model Your Portfolio
Worked examples are useful for understanding mechanics, but they are not a substitute for running the numbers on your actual position.
Tax Reform Lens does that job. Not a marketing piece: a tool we use ourselves and put in front of every Rising Returns client through this transition.
Enter your portfolio as it actually exists. Set your loan structure, income, growth assumption, rent growth, inflation. Hit run.
You see, side by side:
- Year 1 out of pocket under current law versus post 2027
- Borrowing capacity impact when serviceability tightens
- 10-year cumulative cashflow so the compounding gap is visible
- CGT at exit with the apportioned 50% on gains accrued before 2027 and the new 30% minimum on post 2027
- New build CGT method choice auto-evaluated to pick whichever gives the lower bill
- Net cashflow projection across the 2027 transition, year by year
Real ATO maths. Grandfathering rules. New build treatment. Trust structures. It does not invent numbers and it does not flatter the result.
Run Tax Reform Lens on your portfolio in about 60 seconds.
The Principles That Still Win
★(1) Buy on growth fundamentals, not tax fundamentals. A property growing 5% a year produces $42,500 of growth on an $850,000 base in year one which dwarfs any plausible tax outcome, so tax was always the secondary engine and the Budget just exposed who had been treating it as the primary one.
★(2) Choose suburbs with structural demand drivers. Population growth, infrastructure announcements, gentrification and jobs are what drive long term capital growth, and the suburbs that work after the Budget are the same ones that worked before it.
★(3) Use leverage responsibly. 80% LVR on a property that grows is the most powerful wealth-building lever a regular Australian wage earner has. The Budget did not touch the LVR. It touched the cashflow assumption: make sure your cashflow assumption is real.
★(4) Hold for two cycles, not two years, because of the apportionment most of your gain stays at the 50% discount if you held early enough.
★(5) Run the numbers before you sign, always, and especially now.